
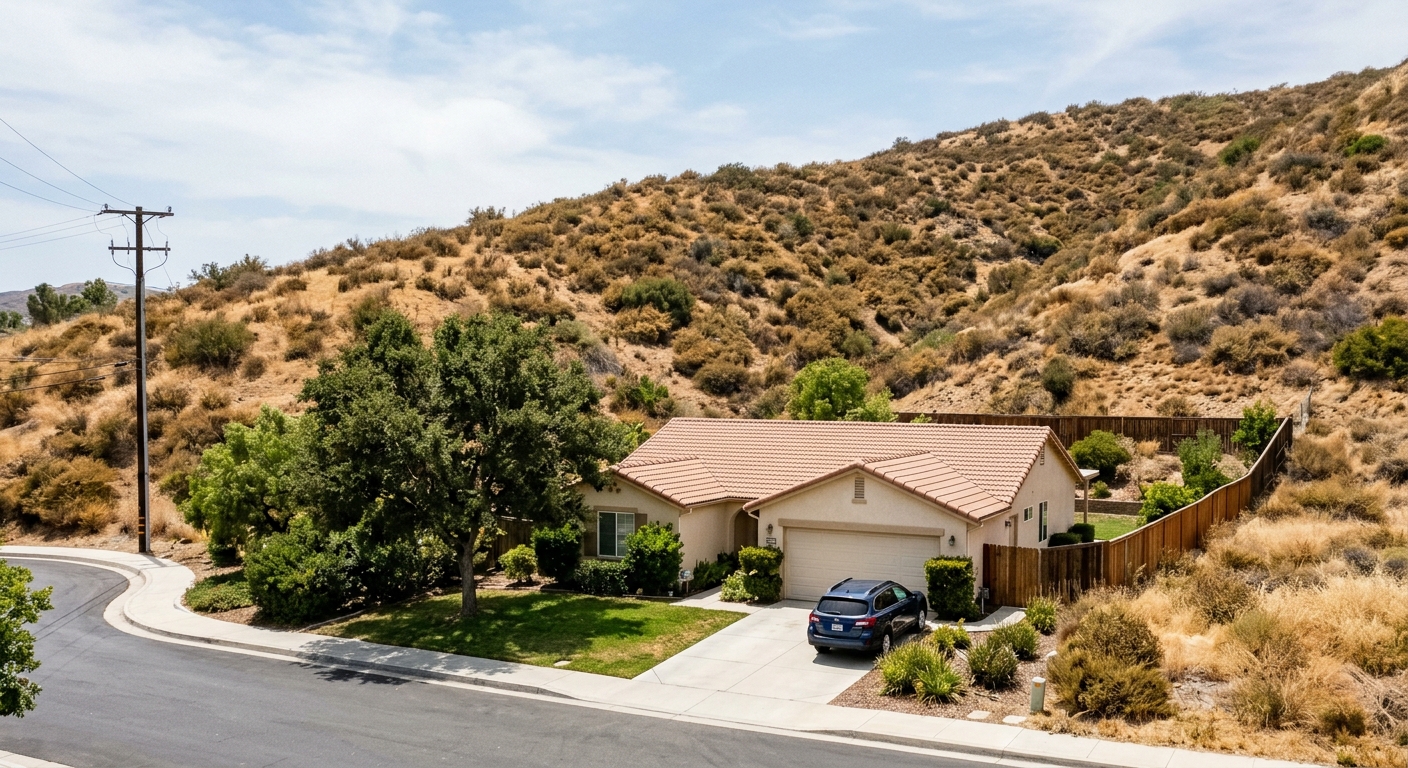
AI-generated illustration; not a photograph of the reported event.
- calendar_today November 15, 2026
Jane Kim’s Vision for Home Insurance Reform
Jane Kim, former San Francisco Supervisor and newly elected California insurance commissioner, campaigned on a bold proposal to address the state's unsettled home insurance market: a state-run wildfire insurance program. Kim's plan, called Natural Disaster Insurance for All, aims to ensure affordable and widely available home insurance by eliminating profit incentives and prioritizing the reduction of wildfire risks.
Background: Catastrophic Wildfires and Market Fallout
California has faced a series of devastating wildfires over the past decade. The January 7, 2025, firestorms in the Pacific Palisades and Altadena areas alone damaged or destroyed over 16,000 structures. These disasters prompted private insurers to drop policyholders in high-risk areas and raise rates. As a result, enrollment in the state's insurer of last resort, the California FAIR Plan, more than doubled to 677,000 residential policies since 2022. These policyholders also faced surcharges to help cover $4 billion in losses from January 2025.
Details of the State-Run Wildfire Insurance Plan
Kim’s plan, influenced by models such as the California Earthquake Authority, proposes that wildfire coverage would become mandatory for homeowners. Commercial insurers would continue offering policies for other risks (like water or theft damage), but wildfire losses would be covered by the state plan, which holds the risk and funds claims. Premiums would account for each home's specific wildfire risk and rebuild costs, plus a capped fee to build reserves for especially severe seasons.
The coverage amount would be limited to the cost of rebuilding a typical California home, allowing owners of more expensive properties to buy supplemental coverage on the open market. This approach focuses support on "ordinary homeowners." The plan's eligibility for new homes would depend on their assessed wildfire risk and mitigation efforts.
Industry and Advocacy Response
While Kim’s initiative was outlined in her October policy brief, critics, including state Sen. Ben Allen, have noted that significant details remain unresolved—especially regarding startup financing and claims management. The American Property Casualty Insurance Association and other industry representatives have expressed concerns about the feasibility of such a sweeping change.
Insurance experts highlight the challenges in staffing enough adjusters for a catastrophe-centered program. Chuck Nyce of Florida State University points out the trade-offs between using state-hired adjusters or relying on private insurers to manage claims, each carrying cost and incentive implications. There is ongoing investigation by the California Department of Insurance and Los Angeles County into the claims-handling practices of major insurers, following consumer complaints after recent fires.
Financial Hurdles and Funding Options
One of the most significant obstacles is securing startup capital. A state-commissioned study estimated up to $25 billion would be needed, with suggestions to fund the program via bond sales, assessments, or reinsurance. Heavy reliance on reinsurance could reduce the capital required to $6 billion, but may increase aggregate homeowner premiums from $18 billion to over $20 billion annually.
Carmen Balber of Consumer Watchdog cautioned that heavy use of reinsurance could result in higher premiums or higher deductibles, drawing comparisons to the California Earthquake Authority, which has faced similar issues. Premiums for CEA coverage fluctuate widely based on a home’s characteristics and can be significant for homeowners.
Policy Prospects and Next Steps
Kim’s policy brief also considers whether to require existing insurers to contribute startup capital proportional to their market share, a move likely to provoke opposition from the insurance industry. Rex Frazier of the Personal Insurance Federation of California highlighted that market reforms are already encouraging some insurers to write new policies, although the pace of FAIR Plan growth has slowed recently.
Despite unresolved questions around claims administration, financing, and regulatory structure, Kim remains committed to negotiating with legislative and industry stakeholders. She suggests the outcome might be a public-private partnership or another compromise, always centered on consumer needs. Amy Bach of United Policyholders emphasized the scale of the challenge but expressed willingness to support a viable solution to the state’s home insurance crisis.
Source: latimes.com.
Recent Posts

Hot Categories

155
Business

74
Events

220
News
83
Sports
120
Technology

